
By Joseph Bryson October 7, 2026
Choosing between a registered ISO vs sales agent comes down to control, economics, and risk. A registered ISO can gain stronger branding, pricing and portfolio rights, but it also takes on sponsor-bank diligence, network registration, compliance overhead and contractual loss exposure. Staying an agent usually means less control, but materially lower fixed cost and liability.
For someone already selling merchant services, becoming a registered Independent Sales Organization can look like the obvious next step. You may keep more of the processing margin, recruit your own sales organization, build a recognizable brand, and create a portfolio that may eventually be sold.
But registration is not simply an upgraded commission plan.
It changes the relationship among your company, the acquiring bank, processor, card networks, sales agents, and merchants. It also introduces costs and obligations that do not exist—or are absorbed upstream—when you operate as an independent agent.
The right registered ISO vs sales agent decision therefore starts with four questions:
- How much more net residual will registration actually produce?
- What will registration and ongoing compliance really cost?
- What liabilities will the sponsor bank push back to the ISO by contract?
- Will the resulting portfolio be more valuable and transferable?
Those questions matter more than whether your portfolio has reached an arbitrary merchant count or processing-volume threshold.
Registered ISO vs Sales Agent: What Actually Changes?
A sales agent generally operates underneath an ISO, processor, or merchant-services organization. The upstream company maintains the acquiring relationship and card-network registrations while the agent focuses primarily on finding and supporting merchants.
A registered ISO sits closer to the acquiring bank.
Visa treats an Independent Sales Organization as a type of Third Party Agent, while Mastercard classifies ISO activity as a Service Provider program service that can include merchant solicitation, application processing, customer service, merchant education, and terminal deployment. Mastercard’s June 2, 2026 Rules expressly identify these activities under its ISO Program Service category.
That distinction creates more business control, but it does not turn the ISO into a bank.
| Issue | Independent Sales Agent | Registered ISO |
| Card-network relationship | Operates under an upstream organization | Registered through applicable acquiring/sponsor relationships |
| Sponsor bank relationship | Usually indirect | Direct contractual relationship is normally required for the program |
| Merchant pricing | Controlled by upstream agreement | Usually more flexibility within sponsor-approved parameters |
| Branding | Often upstream or co-branded | Greater ability to build an ISO brand, subject to network and sponsor rules |
| Residual economics | Receives an agreed agent split | May retain a larger portion before paying downstream agents |
| Recruiting agents | Usually limited by agent contract | Can potentially build an agent hierarchy |
| Compliance overhead | Lower | Significantly greater |
| Network registration costs | Usually absorbed upstream | Generally becomes part of the ISO’s economics |
| Risk exposure | Defined by agent contract | Often broader contractual indemnity and loss exposure |
| Portfolio control | Depends heavily on upstream contract | Potentially stronger, but still depends on the sponsor and processing agreements |
| Exit value | Value rests mostly in residual rights | Can create a more institutionally structured asset if contractual rights are strong |
Understanding the layers is easier when you separate the merchant account, processor, and acquiring relationship. The distinction between those functions is explained further in merchant account vs payment processor roles.
The critical point is this:
A registered ISO gains a stronger operating position. It does not automatically become the acquiring institution, BIN owner, processor, or legal owner of every merchant relationship.
Who Actually Owns the Merchant Agreement?
This is one of the most misunderstood parts of the registered ISO vs sales agent discussion.
People in merchant services frequently say things such as:
“Once you become registered, the merchant agreement becomes yours.”
That statement is too broad.
Visa’s April 2026 rules state that an acquirer must have a Merchant Agreement with each merchant whose Visa transactions it acquires.
Mastercard’s June 2, 2026 Rules are even more explicit. They state that the Merchant Agreement establishes the acquiring relationship between the acquirer and merchant. A Service Provider may participate as a party, but the acquirer must remain responsible for and in control of the Service Provider’s performance.
So registration does not remove the acquiring bank from the legal structure.
Merchant agreement, merchant relationship, and residual rights are different assets
There are really three questions:
Who is legally responsible for the acquiring relationship?
The acquirer remains central under card-network rules.
Who controls the day-to-day merchant relationship?
That may be the registered ISO, depending on the sponsor bank agreement and processing arrangement.
Who has the economic right to the residual?
That is determined by contract.
Those distinctions become extremely important when an ISO is sold.
A company can service merchants under its own brand and receive residual income for years without having an unrestricted right to transfer those merchants or residuals to another buyer.
Residual ownership comes from the contract—not the ISO registration
A registered ISO should examine provisions covering:
- Vesting
- Post-termination residual payments
- Assignment
- Change of control
- Merchant solicitation
- Merchant portability
- Processor consent
- Sponsor consent
- Residual offsets
- Indemnification
- Termination for cause
- Agent ownership
- Servicing obligations
Receiving a residual payment every month is not the same as possessing an unconditional, transferable ownership interest.
This is why portfolio buyers evaluate contract rights alongside revenue history. The relationship between residual cash flow, attrition, concentration, transferability, and buyer valuation is covered in more detail in how ISO residual portfolios and buyouts are valued.
Whose Brand Goes on the Merchant Paperwork?
Registered status usually gives the ISO more branding flexibility, but the sponsor still matters.
Visa requires members to control solicitation activity and approve Third Party Agent marketing materials. Its current rules also say that when applicable solicitation materials display Visa marks, the member must be appropriately identified and the merchant agreement remains between the member and merchant.
Mastercard similarly requires an acquiring Service Provider using Mastercard marks in certain materials to identify itself as an agent of the applicable customer/acquirer.
That means becoming registered does not create unlimited white-label freedom.
Your company may become the merchant-facing brand, but the sponsor/acquirer cannot simply be erased from the legal and network structure.
A prospective ISO should therefore review:
- DBA and trade-name approval
- Merchant-application branding
- Website disclosures
- Acquirer identification
- Card-network mark usage
- Statement branding
- Customer-support identification
- Contract signature structure
Brand control has value, but it should not be confused with acquiring authority.
What Does ISO Registration Actually Cost?
The most searched question about how to become a registered ISO is often:
How much are the Visa Mastercard ISO registration fees?
Unfortunately, many articles answer that question with numbers copied from older industry material without checking the current primary sources.
That creates a problem.
What the current rules actually confirm
Visa’s current Third Party Agent program says most agents requiring sponsored activities register through a Visa Client sponsor. Visa’s April 2026 rules also require applicable Third Party Agents to be registered before performing covered activities and require ongoing sponsor oversight. Visa Third Party Agent Registration program
Visa does have a public FAQ that lists $5,000 for initial ISO registration and $5,000 for annual renewal, but that document is dated May 2016.
It should therefore be treated as historical public guidance rather than represented as a guaranteed 2026 sponsor invoice.
Mastercard’s June 2, 2026 Rules confirm that after a Service Provider is registered, Mastercard charges the registering Customer an initial registration fee and applicable annual renewal fee. The public rule text does not state a dollar amount.
The practical answer on Visa Mastercard ISO registration fees
If you are preparing a 2026 business plan, request a current written fee schedule from the sponsor or acquiring partner.
Do not build the model around a blog post saying:
- Visa = $5,000
- Mastercard = $5,000
- Therefore registration = $10,000.
The actual amount billed to the ISO can depend on the current network schedule, how the sponsor passes through those charges, additional sponsor fees, the number of registrations or relationships involved, and the services being registered.
The registration fee is not the real cost of being an ISO
A better cost model looks like this:
| Cost Category | What to Budget For |
| Network registration | Current Visa/Mastercard charges passed through or billed under the sponsor arrangement |
| Sponsor onboarding | Due diligence, implementation, administration, or program charges if applicable |
| Legal | Sponsor agreement, processor agreement, agent agreements, merchant-facing documents |
| Insurance | E&O, cyber, crime, general liability, or other coverage required by the sponsor |
| Compliance | Compliance staff, consultants, monitoring, policy maintenance |
| PCI/data security | Depends on systems and cardholder-data involvement |
| Risk operations | Merchant monitoring, fraud review, disputes and exception management |
| Sales oversight | Agent onboarding, marketing approval and sales-practice monitoring |
| Technology | CRM, boarding tools, reporting, residual calculation, ticketing |
| Accounting | Merchant-level residual reconciliation and downstream agent payments |
| Capital/reserves | Any security deposit, reserve, guarantee or liquidity requirement imposed contractually |
Some of these costs may not apply to every ISO. Others can become substantial.
That is why ISO registration requirements should be evaluated as an operating model rather than a filing fee.
What Does a Sponsor Bank Require to Register an ISO?
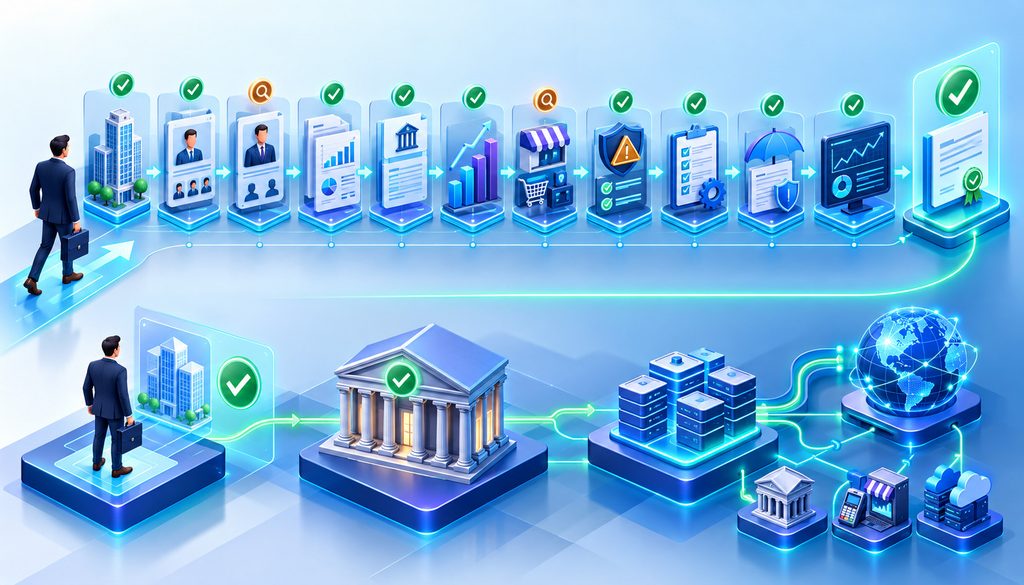
The acquiring or sponsoring relationship is one of the biggest differences between an agent and a registered ISO.
Visa says most agents need a Visa Client sponsor. The sponsor acts as the liaison with Visa and is responsible for making sure the agent meets applicable eligibility requirements, Visa Rules, and local regulations.
Visa’s registration materials identify information such as the sponsor, TPA category, services provided, and applicable PCI documentation among onboarding items.
Visa’s April 2026 rules go further. Before registration, the member must complete applicable due diligence, and registered Third Party Agents are subject to annual review. Visa also requires an on-site inspection as part of applicable TPA due diligence, including review of solicitation materials, operational controls, and security practices.
What a sponsor may ask you to provide
There is no universal sponsor-bank checklist that applies identically to every ISO.
A serious applicant should nevertheless be prepared for diligence in these areas.
Ownership and management
Expect requests for information covering:
- Legal entity structure
- Beneficial owners
- Company principals
- Executive biographies
- Relevant payments experience
- Litigation or regulatory history
- Prior ISO or processor relationships
- Background checks
- Business locations
- DBA names
- Related companies
The sponsor needs to understand who is operating under its acquiring relationship.
Financial condition
Common sponsor diligence may include:
- Business financial statements
- Balance sheet
- Profit-and-loss statements
- Bank statements
- Tax returns
- Existing residual statements
- Capitalization
- Debt
- Cash liquidity
- Processing forecasts
- Merchant concentration
- Historical chargeback or loss information
These requirements should not be presented as universal Visa or Mastercard mandates. The exact financial package is determined by the sponsor’s underwriting and risk program.
But the logic behind the review is straightforward.
A sponsor accepting responsibility for an ISO needs confidence that the organization can operate properly, fund its obligations, maintain staff and controls, and survive a material merchant loss.
For a merchant-level parallel, how merchant account approval requirements work explains why processors and acquirers examine financial condition, transaction patterns, business model, ownership, and chargeback exposure before approving processing relationships.
Sales and volume expectations
A prospective sponsor may want to know:
- Expected monthly processing volume
- Number of merchants expected to board
- Average merchant size
- Average transaction amount
- Target industries
- Card-present versus card-not-present mix
- Geographic footprint
- Number of sales representatives
- Acquisition channels
- High-risk exposure
- Expected portfolio growth
A volume commitment is usually a commercial sponsor term, not a universal card-network rule.
That distinction matters.
If one sponsor requires $X in production or a certain number of monthly boardings, do not describe that threshold as a Mastercard or Visa ISO registration requirement.
Risk and compliance policies
A serious sponsor bank agreement may also require formal procedures for:
- Merchant screening
- Prohibited businesses
- Sales practices
- Application accuracy
- Merchant monitoring
- Chargebacks
- Fraud
- Complaints
- Data security
- PCI compliance
- Agent oversight
- Marketing approval
- Escalation
- Recordkeeping
- Regulatory compliance
The larger your sales organization becomes, the more important these controls become.
How to Become a Registered ISO: A Practical Sequence
If you are researching how to become a registered ISO, the process is better understood as a sequence of business decisions rather than an application form.
1. Build the company before applying for the title
Establish the legal entity, ownership structure, operating bank account, accounting system, insurance, written policies, management team, and financial records.
A sponsor reviewing an ISO applicant is evaluating an operating company.
2. Define exactly what the ISO will do
Determine whether your company will perform only merchant solicitation and customer support or whether it will also perform activities involving:
- Merchant onboarding
- Application processing
- Pricing
- Equipment deployment
- Chargeback assistance
- Transaction information
- Gateway services
- Data storage
- Risk monitoring
Different functions create different compliance and technology obligations.
3. Build the economics before negotiating registration
Know your existing agent economics.
For each merchant, calculate:
Gross processing revenue
− processor/acquirer costs
− upstream ISO share
= current agent residual
Then model the registered structure:
Gross processing revenue
− processor/acquirer costs
− sponsor costs
− agent payouts
− ISO operating overhead
− expected risk cost
= registered ISO contribution
Registration should improve the second number enough to justify the additional infrastructure.
4. Compare sponsor agreements—not only processor pricing
A low processing cost does not compensate for a bad sponsor bank agreement.
Evaluate:
- Residual ownership
- Vesting
- Indemnification
- Reserves
- Personal guarantees
- Residual offsets
- Pricing authority
- Underwriting authority
- Agent appointment rights
- Merchant ownership language
- Termination rights
- Post-termination residuals
- Assignment
- Change of control
- Portfolio sale rights
- Data access
- Reporting
- Sponsor audit rights
Have payments counsel review the final agreements before relying on them economically.
5. Complete sponsor due diligence
Provide the requested financial, ownership, operational, compliance and business-plan materials.
Be prepared to explain your vertical strategy and how you prevent unsuitable merchants from entering the portfolio.
6. Complete the applicable card-network registration
The sponsor submits or supports the applicable registration.
Visa’s current rules require covered Third Party Agents to be registered before contracted services begin. Mastercard similarly requires written confirmation of Service Provider registration before the applicable Program Service begins.
7. Treat registration as an ongoing obligation
Registration is not “approved once and forgotten.”
Visa requires annual TPA review by the sponsoring member. Mastercard requires information necessary to maintain registration and provides for annual renewal fees.
Your compliance cost therefore continues after approval.
Where Does the Liability Sit After Registration?
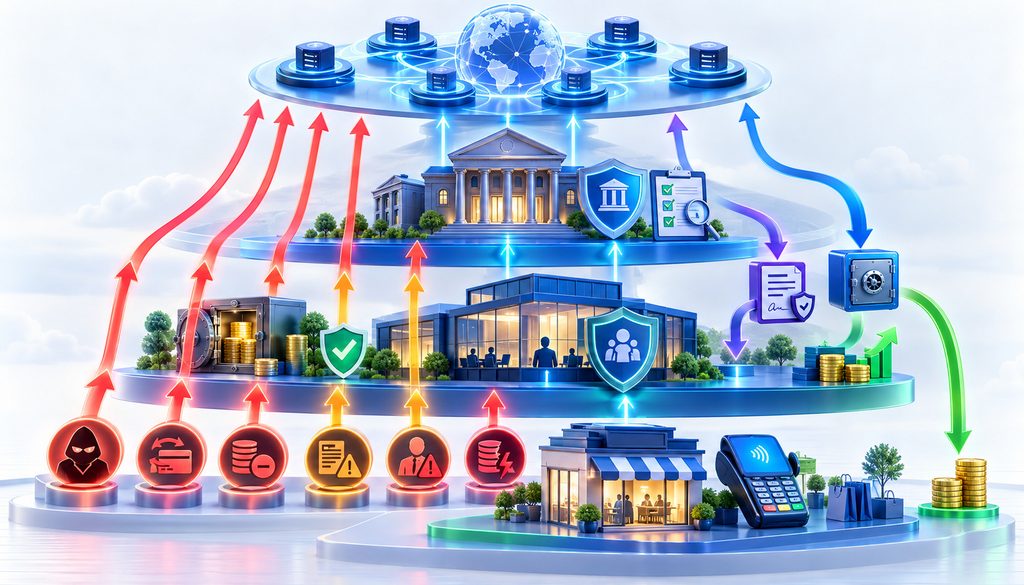
This is where economics becomes more interesting.
People sometimes describe registration as the point where all card-network liability moves from the sponsor bank to the ISO.
That is not accurate.
Network responsibility remains with the acquirer/sponsor
Visa’s April 2026 rules require the member using a Third Party Agent to control merchant approval and review, control establishment of merchant transaction fees, and accept responsibility for applicable fees and losses caused by the Third Party Agent.
Visa also states that members remain responsible for card activities performed directly or indirectly through Third Party Agents.
Mastercard likewise states that the merchant agreement must reflect the acquirer’s primary responsibility for the acquiring relationship. Even when a Service Provider participates in the Merchant Agreement, the acquirer remains responsible and in control.
That means the registered ISO does not become the sponsor bank at the network level simply because it has an ISO registration.
Contractual loss allocation can still move back to the ISO
Here is the important economic distinction:
Network responsibility and contractual indemnity are not the same thing.
The sponsor may owe obligations to the card network.
The ISO may then owe the sponsor reimbursement under its sponsor bank agreement.
That can expose the ISO to losses involving:
- Fraudulent merchants
- Negative merchant balances
- Chargebacks
- Merchant bust-out fraud
- Incorrect merchant applications
- Misrepresentation by agents
- Prohibited businesses
- Network assessments
- PCI or data-security failures
- Regulatory complaints
- Unapproved marketing
- Merchant-monitoring failures
- Contract breaches
This is where merchant services agent liability can look very different from registered-ISO liability.
An ordinary salesperson might lose commissions or face a limited clawback.
A registered ISO may have a broader indemnity covering losses attributed to its merchant portfolio or sales organization.
Does a Registered ISO Have BIN-Level Responsibility?
Not automatically.
This deserves a direct answer because the phrase is often used incorrectly.
A registered ISO normally operates through an acquiring institution’s network relationship. Registration as an ISO is different from becoming a Visa-licensed acquirer, Mastercard principal customer, or other direct network member with its own acquiring identifiers.
The registered ISO may operate merchant relationships associated with the sponsor’s acquiring structure, but that does not make the ISO itself the BIN licensee simply because it registered.
Visa’s rules distinguish Third Party Agents from members and assign responsibilities through the member/sponsor structure. Mastercard’s rules likewise require the acquirer to retain responsibility for the merchant acquiring program.
The sponsor bank agreement may nevertheless make the ISO economically responsible for many losses connected with merchants it sourced.
That is the risk that needs to be modeled.
Why One Bad Merchant Can Change the ISO Economics
Consider a hypothetical ISO earning:
- $70,000 monthly gross residual
- $25,000 downstream agent payouts
- $20,000 operating overhead
That leaves:
$25,000 monthly operating contribution
Now assume a merchant creates a $175,000 unrecoverable negative balance and the sponsor agreement permits that amount to be offset against ISO residuals.
That loss represents seven months of the ISO’s normal operating contribution.
The portfolio may still be profitable over time, but its risk profile looks very different from a commission-only agent arrangement.
That is why registered-ISO profitability should be measured as:
Net residual − overhead − expected loss cost
not simply:
Processing markup − agent commission
When Does ISO Registration Pay for Itself?
There is no universal monthly processing volume at which becoming a registered ISO suddenly makes sense.
The correct break-even point depends on margin.
Use residual economics instead of processing volume
Let:
A = Current annual agent residual
I = Expected annual registered ISO residual before additional overhead
C = Additional annual compliance, registration and operating cost
R = Expected annual risk cost
Then:
Registration Advantage = I − A − C − R
If that number is materially positive and remains positive under conservative assumptions, registration may be economically justified.
Example 1: Large volume, weak improvement
Suppose an agent portfolio produces:
- $90 million monthly processing volume
- $55,000 monthly agent residual
Registration would improve retained residual by only $3,500 per month.
Incremental annual residual:
$3,500 × 12 = $42,000
If additional ISO overhead is $50,000 annually before loss exposure, registration produces worse economics despite the impressive processing volume.
Example 2: Smaller portfolio, stronger economics
Another agent processes only $30 million monthly but gives up substantial margin to an upstream ISO.
Registration increases retained residual by $10,000 per month.
Incremental annual residual:
$10,000 × 12 = $120,000
If additional fixed cost is $55,000 and expected risk cost is $15,000:
$120,000 − $55,000 − $15,000 = $50,000
The smaller portfolio creates the stronger registration case.
These examples are illustrative, not industry benchmarks.
Include pricing structure in the model
Residual economics ultimately come from the spread between merchant revenue and upstream cost.
If the portfolio primarily uses transparent cost-plus pricing, understanding the processor’s underlying markup helps identify how much margin can realistically be retained at the ISO level. The mechanics are explained in interchange-plus pricing and processor markup.
The important metric is not gross card volume.
It is sustainable net residual per merchant after all costs and loss assumptions.
What Should the Break-Even Worksheet Include?
Before changing structures, model at least three cases.
| Item | Current Agent | Registered ISO |
| Monthly processing volume | — | — |
| Gross portfolio revenue | — | — |
| Upstream processing cost | — | — |
| Agent/downstream splits | — | — |
| Sponsor charges | Included upstream | — |
| Network registration | Included upstream | — |
| Compliance staff/vendor | Minimal | — |
| Legal/insurance | — | — |
| Technology/reporting | — | — |
| Expected loss provision | — | — |
| Net monthly residual/contribution | — | — |
Then run:
- Base case: current expectations.
- Stress case: merchant attrition rises and margin compresses.
- Loss case: a large negative merchant event occurs.
If registration only works under the best-case scenario, it probably does not yet justify the additional responsibility.
What About a Sub-ISO?
A sub-ISO can provide a middle path.
“Sub-ISO” is usually an industry and contractual description rather than one universal network category with identical rights everywhere.
A sub-ISO may receive:
- Better residual splits
- Merchant-level reporting
- More branding
- Agent recruiting rights
- Dedicated pricing
- Increased support authority
- Portfolio-management tools
while remaining underneath a larger registered organization.
For a productive sales office that is not ready to maintain its own sponsor relationship, this can be attractive.
But do not judge a sub-ISO arrangement by the title.
Review:
- Who receives processor payments?
- Are residuals vested?
- What happens after termination?
- Can merchants be moved?
- Can the residual stream be assigned?
- Who controls pricing?
- Can the upstream ISO offset unrelated losses?
- Who owns downstream agent contracts?
- What happens if the upstream ISO is sold?
Those terms determine whether the arrangement behaves like a valuable business or simply a richer agent agreement.
What Is a “Registered Agent” or “Registered Rep”?
This language creates even more confusion.
Processors and ISOs may use labels such as:
- Registered rep
- Registered agent
- Sales office
- Independent office
- Sub-ISO
- Referral partner
- Partner
- Dealer
Those titles do not necessarily mean the company itself holds a direct Visa or Mastercard ISO registration.
Ask:
- Which legal entity is actually registered?
- Which acquiring institution sponsors that registration?
- Which company receives processor residuals?
- Whose contract governs the merchants?
- What rights survive termination?
If the answers still point entirely to the upstream ISO, the organization may remain functionally closer to an agent even if its marketing title sounds more independent.
How Does Registered ISO Status Affect Portfolio Value?
Registration can improve portfolio valuation, but registration itself is not the asset.
The asset is durable cash flow backed by enforceable rights.
Buyers commonly care about:
- Normalized residual
- Merchant retention
- Residual-dollar attrition
- Merchant concentration
- Industry concentration
- Processing history
- Margin stability
- Contract quality
- Assignment rights
- Sponsor dependence
- Processor dependence
- Agent concentration
- Merchant servicing burden
- Chargebacks and fraud
- Pending liabilities
Why registered ISOs can sometimes command stronger valuations
A mature registered ISO may offer a buyer:
- Cleaner merchant-level reporting
- Stronger control over downstream agents
- Better-documented residual economics
- Direct sponsor/processor contracts
- Formal operating infrastructure
- A recognized merchant-facing brand
- More predictable servicing processes
- Contractual rights that are easier to diligence
Those factors can make the portfolio more institutional.
Why registration can also reduce value
A registered ISO can simultaneously carry:
- Broad indemnification
- Sponsor concentration
- Personal or corporate guarantees
- Reserve exposure
- Difficult assignment clauses
- Unresolved network issues
- Merchant-risk concentration
- High fixed compliance costs
A buyer will price those liabilities.
Two portfolios producing identical residuals can therefore receive very different offers.
Exit value depends on transferability
A useful question is not:
“Do I own these merchants?”
Ask:
“What precisely can I transfer to a buyer without violating my sponsor, processor, merchant, or agent agreements?”
That may include:
- Residual rights
- Stock or membership interests in the ISO entity
- Agent agreements
- Servicing rights
- Customer relationships
- Intellectual property
- Brand
- Technology
- Employees
Some of those rights may require consent.
This becomes especially important during acquisitions and processor migrations. What happens when an ISO is sold or a processor changes platforms explains why ownership changes, portfolio transfers, acquiring relationships, merchant contracts and processor migrations should be treated as separate events.
Registered ISO vs Sales Agent: A Decision Scorecard
Registration deserves serious consideration when most of these statements are true:
- Your residual portfolio is already large and stable.
- The incremental margin is meaningful after all additional costs.
- Merchant attrition is controlled.
- You have diversified sales production.
- You can support compliance staff and processes.
- You understand merchant underwriting and risk.
- Your sponsor offers commercially reasonable indemnification terms.
- You can negotiate meaningful residual ownership.
- You want to build a downstream agent organization.
- Portfolio valuation and eventual sale matter to you.
- You can survive a substantial merchant loss.
- You have legal counsel experienced in payments contracts.
Remaining an agent or sub-ISO may make more sense when:
- Your current residual split is already attractive.
- Registration produces only a small margin improvement.
- One salesperson or merchant dominates production.
- You do not want compliance operations.
- You do not have sufficient liquidity for portfolio losses.
- Your sponsor would require extensive guarantees.
- Your volume is growing but residual economics remain thin.
- You primarily want to sell rather than operate a payments company.
The point is not that one structure is better.
The right structure depends on what business you actually want to own.
Eight Questions to Ask Before Signing a Sponsor Bank Agreement
Before becoming registered, get written answers to these questions.
- What are the current Visa Mastercard ISO registration fees being passed through to us?
- What additional sponsor, administration, minimum-production, implementation or renewal charges apply?
- Which losses can the sponsor deduct from our residual?
- Are there reserve, guarantee, insurance or capital requirements?
- Do residual payments survive termination, and under what conditions?
- Can residual rights or the company itself be sold without sponsor approval?
- Who controls merchant pricing, underwriting, termination and agent appointments?
- What happens to the portfolio if the sponsor relationship ends?
A ninth question is worth adding:
Could a sub-ISO arrangement deliver most of the economic benefit without the same fixed cost and liability?
That comparison prevents registration from becoming an ego-driven decision.
Frequently Asked Questions
What is the simplest difference between a registered ISO and a sales agent?
A sales agent normally sells under another merchant-services organization’s acquiring and registration infrastructure. A registered ISO has its own approved ISO relationship within the sponsor/acquirer structure and typically gains more control over branding, pricing economics, agent management and portfolio operations. The registered ISO also assumes materially more operating responsibility.
When should I become a registered ISO instead of staying an agent?
Consider registration when your incremental residual is large enough to cover registration, sponsor, compliance, insurance, legal, technology and risk costs with a meaningful margin remaining. There is no universal monthly processing-volume threshold.
How much are Visa Mastercard ISO registration fees?
The safest answer in 2026 is to obtain current written pricing from the sponsor. Visa’s older 2016 public FAQ listed a $5,000 initial and annual ISO fee, but that document is not current enough to treat as a guaranteed 2026 price.
Mastercard’s June 2026 Rules explicitly state that initial and annual Service Provider registration fees apply, but the public rule text does not give the dollar amount.
What are the main ISO registration requirements?
Typical ISO registration requirements include a sponsor/acquirer relationship, business and ownership information, defined services, required network registration, applicable financial and compliance due diligence, and ongoing sponsor oversight. Requirements vary according to network category, region, services provided and sponsor risk policy.
Does the sponsor bank require financial statements?
Frequently, yes, as part of sponsor diligence, although the exact financial package is sponsor-specific. A sponsor may request business financials, bank statements, residual history, forecasts, ownership information, capitalization data and other materials needed to evaluate financial stability and risk.
Do sponsor banks require minimum processing volume?
They may.
A volume commitment or minimum production requirement is generally a commercial term imposed by the sponsor or processor, not a universal Visa or Mastercard requirement. That distinction should be clear in any business plan.
Who is liable for merchant fraud when I become a registered ISO?
At the card-network level, the acquirer or sponsoring member continues to carry responsibilities defined by network rules.
At the contractual level, however, the sponsor bank agreement may require the registered ISO to indemnify the sponsor for fraud losses, negative merchant balances, chargebacks, assessments or other losses tied to the ISO’s merchants or agents.
That is why liability provisions require careful legal review.
Can a sub-ISO own residuals?
Potentially.
Residual rights come from the sub-ISO agreement. Examine vesting, transferability, termination, offset and assignment language rather than relying on the “sub-ISO” title.
Registered ISO vs Sales Agent: Which Structure Makes More Sense?
The registered ISO vs sales agent decision should ultimately be made from economics and contractual control—not industry status.
Registration makes sense when the additional margin is large enough to pay for the infrastructure, your portfolio is mature enough to support the fixed cost, the sponsor agreement gives you meaningful long-term rights, and your company can absorb the operational and financial consequences of managing merchant risk.
Staying an agent can be the smarter business decision when your existing split is competitive and an upstream organization is absorbing underwriting infrastructure, card-network registration, compliance operations, sponsor management and portfolio risk on terms that would be expensive to reproduce yourself.
A sub-ISO arrangement can provide a useful middle step when you want better economics and branding without immediately assuming the complete registered-ISO operating burden.
Leave a Reply